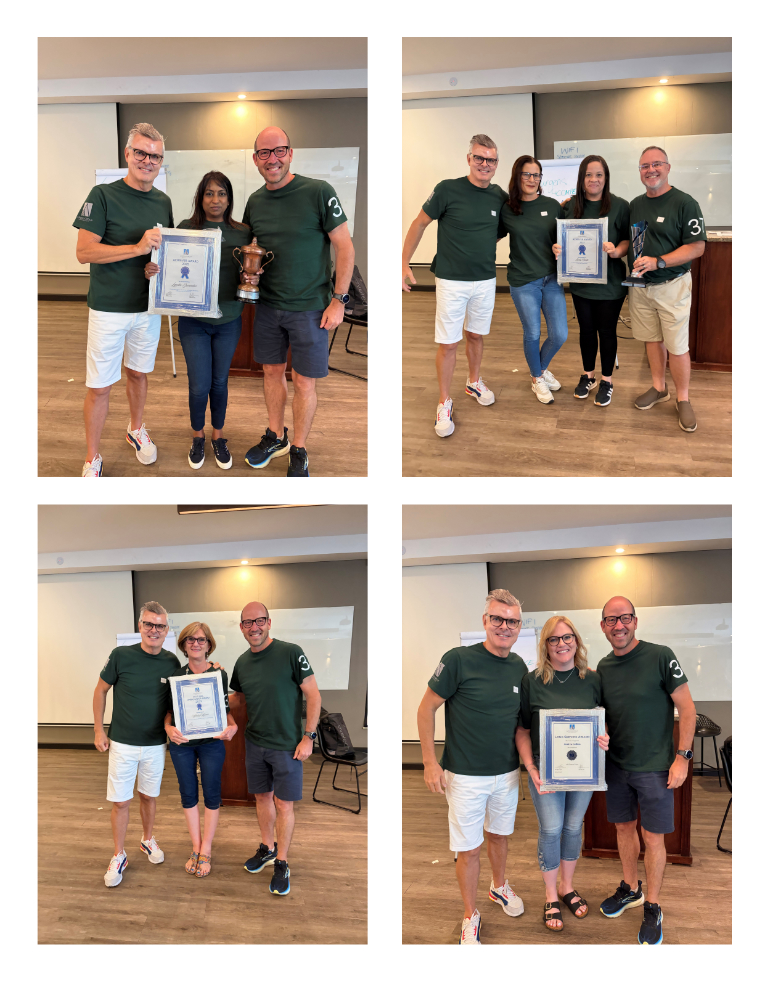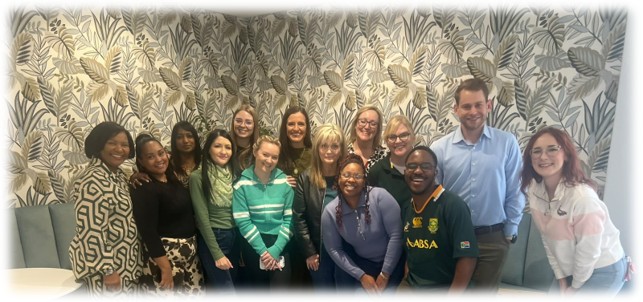

We recently celebrated a special milestone with Ninety One, our valued partner since 1991. This achievement is a wonderful reflection of our longstanding relationship, built on trust, collaboration and a shared commitment to our clients. A fantastic milestone and a partnership we are proud to celebrate!
A Message from Mark Jurgens
I thought I would use this opportunity to talk about structured products and where they can fit into an investment portfolio.
We have used them selectively over the past decade and have generally been pleased with the results. They have helped us achieve the goals we set for that part of our clients’ portfolios.
Many investors want exposure to share markets but worry about sharp falls. Depending on its terms, a structured product can offer some protection against losses, often in exchange for a limit on the potential return. The rules for calculating the outcome are set at the start.
What I find useful is being able to work through the possible outcomes with a client before investing. We can look at what happens if the market rises, goes nowhere or falls. That helps with planning, even though we cannot know which outcome will occur.
Some products offer full capital protection at maturity; others make that protection conditional on how the market performs. In either case, you are relying on the issuer being able to repay you. Selling before maturity can also mean getting back less than you invested.
For illustration, consider a five-year product linked to the price performance of the STOXX Europe 600. This index includes 600 large, medium-sized, and smaller companies across Europe.
Suppose it pays 125% of any positive index return over the five years, with the investment’s total gain capped at 40%.
Also assume that capital is repaid in full if the index finishes no more than 50% below its starting level. If it finishes more than 50% lower, the full index loss applies. In this example, the protection is assessed only at maturity.
| Index change over five years | Outcome at maturity |
|---|---|
| Up 20% | 25% gain on the investment |
| Up 40% | 40% gain, because the cap applies |
| Down 48% | Original capital repaid, with no growth |
| Down 51% | 51% capital loss; 49% of capital repaid |
I see structured products as something to use alongside the core of a portfolio. They can give us exposure to a market where a client has relatively little invested, but they should not replace a long-term growth strategy.
The fixed term can help investors resist the temptation to sell during a difficult market. It also limits flexibility, so I would only consider investing money that a client can leave untouched for the full term.
For that reason, I would keep the allocation modest. Around 5% might be appropriate for some clients, depending on their existing investments, appetite for risk and need for access to their money.
If you would like to talk through whether structured products have a place in your portfolio, please give us a call.
Wishing you a positive final quarter of 2026.
Mark
In Life and Markets Extremes Rarely Last Forever - from Alan Botha
When markets are rising, economies are growing and our investments are performing well, it is remarkably easy to believe that the good times will continue. Equally, when markets fall, headlines become frightening and uncertainty dominates, it can feel as though things will never improve.
History suggests otherwise.
Markets, economies, businesses, and investor sentiment tend to move in cycles. The difficulty is that while we intellectually understand this, emotionally we often behave as though the present will continue indefinitely.
We extrapolate.
Human beings are natural pattern seekers. If something has been working recently, we tend to expect it to keep working.
A share that has doubled can suddenly feel safer than it did before it doubled. A country experiencing political or economic difficulties can become almost uninvestable in people’s minds precisely when expectations are already extremely low.
This is recency bias: giving disproportionate importance to what has happened recently.
We saw elements of this during the technology boom, the Global Financial Crisis, the COVID-19 pandemic and the inflation and interest-rate shock that followed. Each period produced a compelling story about why “this time is different”.
Sometimes it is different. But that does not mean today’s conditions will last forever.
Price and value are not the same thing.
This introduces one of investing’s great trade-offs.
The investments that feel safest can sometimes carry significant risk because everyone already agrees that they are wonderful. Expectations become extremely high and valuations reflect that optimism.
Conversely, investments surrounded by uncertainty can offer opportunity precisely because expectations are so low.
That does not mean buying everything that has fallen or selling everything that has risen. Cheap investments can become cheaper and excellent companies can remain excellent for decades. Some investments never recover.
The point is that every investment has a price, and every price contains expectations about the future.
Good investing therefore requires us to hold two ideas simultaneously: a wonderful business can be a poor investment at the wrong price, while an unpopular asset can become a sound investment if its price adequately compensates for the risks.
South African investors understand this particularly well.
We live in a country where sentiment can move dramatically.
When political uncertainty, weak growth, infrastructure problems, and a weaker rand dominate the headlines, it is tempting to conclude that nothing will ever improve. Equally, a period of political optimism, improved economic prospects or rand strength can quickly change the narrative.
Neither extreme necessarily provides a complete picture.
South Africa has genuine structural challenges. It also has excellent companies, deep capital markets, entrepreneurial businesses, and institutions that have demonstrated considerable resilience.
The appropriate response is not blind optimism or permanent pessimism. It is perspective.
Behaviour matters more than prediction.
This is where wealth management becomes less about predicting what happens next and more about preparing for a range of outcomes.
Nobody consistently knows where markets, currencies, interest rates, or geopolitics will be twelve months from now.
What we can control is how much risk we take, how diversified we are, how much liquidity we maintain and, importantly, how we behave when things become uncomfortable.
Fear encourages us to sell after prices have fallen. Greed encourages us to buy after prices have risen. The fear of missing out (FOMO) convinces us that everyone else knows something we do not.
A worthwhile investment strategy attempts to put guardrails around those emotions.
Sometimes the best decision is to rebalance. Sometimes it is to take advantage of an opportunity. And quite often, the best decision is simply to stick to a sound plan.
Building portfolios for what we cannot predict.
This philosophy sits at the heart of how we think about investing at The Jurgens Group.
Our role is not to pretend that we can consistently predict the next market move. It is to understand each client’s circumstances, objectives, time horizon, tolerance for risk and financial capacity to absorb losses, and then help ensure that their investment strategy remains aligned with their broader financial plan.
Importantly, we also recognise that investment management and wealth management are not the same thing.
Our primary responsibility is to our clients: understanding what they are trying to achieve, providing perspective when markets become emotional, challenging behavioural biases and helping them make good financial decisions over many years.
We then combine this with the investment expertise of Morningstar, our investment partner, bringing additional depth in asset allocation, manager research, portfolio construction, and ongoing investment oversight.
It is a deliberate combination: The Jurgens Group’s understanding of each client and their financial journey, supported by Morningstar’s global investment research and portfolio expertise.
The objective is not to build portfolios that are perfectly positioned for whatever happens next. Nobody can consistently do that.
Instead, we aim to build resilient, well-considered portfolios that recognise uncertainty, diversify across different sources of return and balance risk against opportunity. These portfolios should help clients remain invested through different market environments, in line with their financial plans.
Because successful investing is seldom about correctly predicting the next big event.
It is about building a plan and portfolio capable of surviving many of them.
Good times call for perspective. Difficult times call for it too.
Stay well and regards
Alan
Short Term News Update from Greg Brits
Storm Season Is Coming: Is Your Cover Ready?
Spring has arrived, and with it the start of the summer thunderstorm season. For much of the Highveld, that means heavy rain, lightning, strong winds and hail. A single storm can damage hundreds of vehicles and homes in minutes, and the claims that follow are often avoidable disputes. A little preparation now can save you a lot of stress later.
Check your sums insured
Underinsurance is the most common problem we see at claim stage. Building costs have risen steadily, and a home insured for what it was worth a few years ago may now be well short of its replacement cost. If your sum insured is too low, insurers can apply the “average” clause and pay out only a proportion of your loss, even on a partial claim.
The same applies to household contents, vehicles and business assets. If you’ve renovated, bought new equipment or added valuables, tell us so your cover keeps pace.
Know what your policy covers
Not all policies treat storm damage the same way. It’s worth confirming:
- Excesses: Many policies carry a separate, higher excess for hail or storm claims.
- Electronics: Lightning and power surges can destroy appliances, routers and computers. Check that surge and lightning damage is included.
- Vehicles: Ask whether your policy responds differently to hail damage, and what your options are for repairs.
- Businesses: Consider whether business interruption cover would keep you going if a storm shut your premises down.
Prevent damage before it happens
- Clear gutters, downpipes and drains so water can escape.
- Have loose roof sheets, tiles and damaged waterproofing repaired.
- Trim overhanging branches that could fall onto your roof, vehicles or boundary walls.
- Park under cover when storms are forecast, or use a hail cover if you have no shelter.
- Unplug sensitive electronics during electrical storms.
If you do suffer damage
- Make it safe. Your safety comes first. Stay away from downed power lines and damaged structures.
- Take photos and video. Record the damage before you move or repair anything.
- Limit further loss. Reasonable temporary measures, like covering a broken window or a hole in the roof, are expected. Keep your receipts.
- Contact us promptly. Report the claim as soon as possible. Insurers have notification requirements, and delays can complicate things. Don’t start permanent repairs until the insurer has assessed the damage or authorised the work.
- Don’t start permanent repairs until the insurer has assessed the damage or authorised the work.
Keep your records ready
Claims move much faster when documents are on hand. Keep a home inventory with photos and serial numbers for major items, and store copies of your policy schedule, valuations and receipts somewhere safe, ideally in the cloud so you can reach them even if your property is damaged.
We’re here to help
Now is a good time to review your cover before the first big storm hits, not after. If you’d like us to check your sums insured, look over your policy wording or get a second opinion on your current cover, get in touch. Our team will make sure you’re protected and know exactly what to do if the worst happens.
Best regards,
Jurgens Insurance Brokers Team
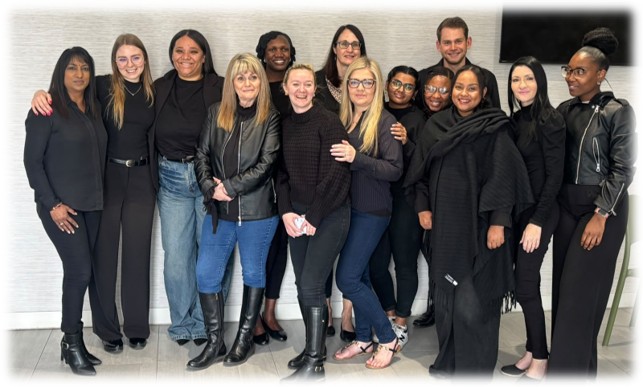
Our Team proudly dressed in black to stand together against Gender-Based Violence (GBV). By wearing black, we joined a collective call to raise awareness, show solidarity with survivors, and take a stand against violence towards women and children.
Together, we can make a difference.
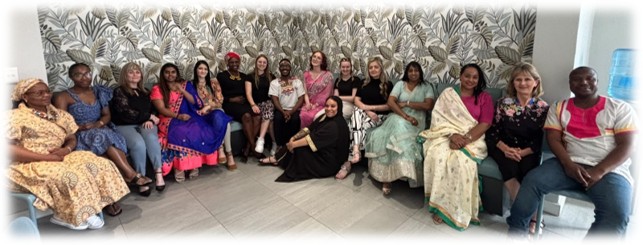
We came together to celebrate Heritage Day, embracing the diverse cultures, traditions and backgrounds that make South Africa so special. It was a wonderful opportunity to celebrate what makes us unique while coming together as one team
Quote of the Day
If you let your learning lead to knowledge, you become a fool. If you let your learning lead to action, you become wealthy.
- Tony Robbins